Banking Regulators Tighten AI Scrutiny. CMOs Should Fund Recovery Before Reassurance.
AI scrutiny by banking watchdogs are making customers nervous. The marketing decision is how to build a customer experience that deflects these fears, build better relationships and make promises the bank can keep.
Take the argument with you.
Read the publication-ready report. Generated from the canonical News article.
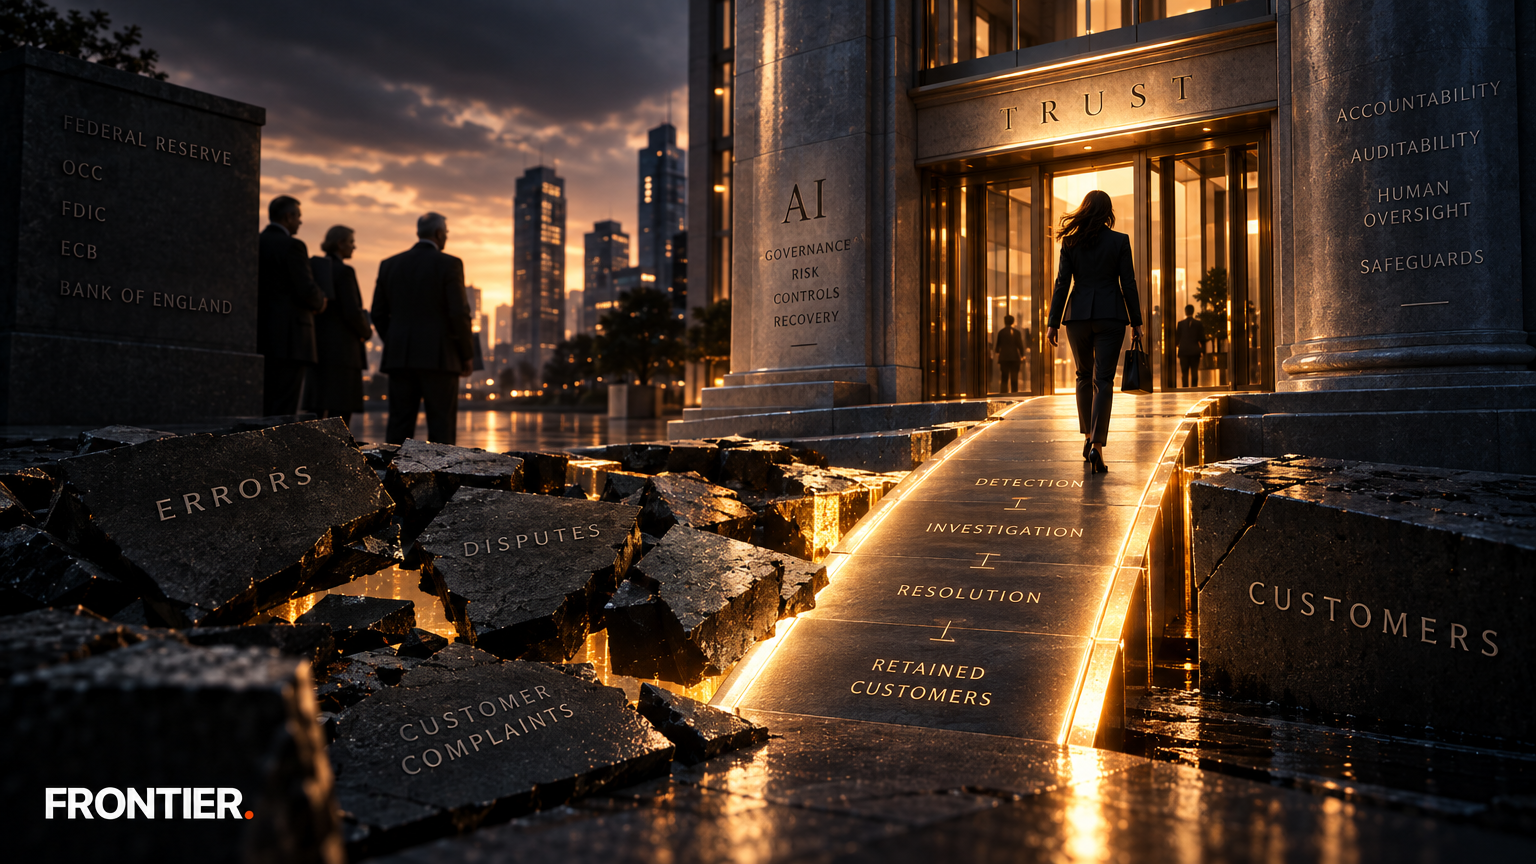
Bank CMOs should answer intensifying AI scrutiny with a customer experience that can recover from mistakes. That is a marketing investment decision, not an attempt to make the CMO the bank’s chief risk officer. Marketing owns the proposition, acquisition spending and much of the relationship strategy. It should not spend money attracting customers to promises that product and service teams cannot reliably deliver.
What changed
On October 13, 2026, Reuters reported, citing six people familiar with the matter, that banking supervisors were increasing scrutiny of advanced AI. Questions from the Federal Reserve, Office of the Comptroller of the Currency and Federal Deposit Insurance Corporation concern agents’ authority, monitoring, auditability, human involvement and shutdown mechanisms. Reuters also reported greater European attention to recovery arrangements. The U.S. agencies and Bank of England declined to comment. This is reporting about supervisory activity, not an announcement of a universal new AI rulebook.1
Public regulatory documents establish the broader direction. The European Central Bank’s July 7, 2026 letter instructed significant institutions under its direct supervision to submit action plans addressing AI-enabled cybersecurity threats by October 31, 2026. Plans must identify measures, resources, responsibilities and implementation timelines, including stronger response and recovery. The deadline does not apply to every bank, nor is it a marketing-compliance deadline.2
The Bank of England’s Financial Policy Committee record, published September 30, 2026, described test-environment incidents involving unexpected autonomous actions under permissive or weakened safeguards. It called for continued preparation against cyber and operational risks. Those observations warrant preparation; they do not establish an imminent banking crisis.3
Customer experience is not absent from regulatory thinking. The UK Financial Conduct Authority’s AI approach, updated October 2, 2026, explicitly connects AI with fair value, understandable communications and appropriate customer support. It also says the authority does not plan to introduce extra AI regulations. More scrutiny and reliance on existing obligations can coexist.4
But regulators don't think the way CMOs do. They must face the reputational and customer experience impacts that lead to customer defections and degraded brand loyalty. It is a strong reason to make customer promises conditional on demonstrated service capabilities.
Why it matters
Consider a scenario, not an observed incident: an assistant incorrectly explains an account restriction, the customer cannot reach someone empowered to help, and automated cross-selling continues while access remains unresolved. A technical error becomes a service cost, a complaint and a reason to reconsider the relationship. The promotional message is not the original failure. It makes the bank appear indifferent to it.
There is evidence of relationship leakage, but not evidence that AI caused it. J.D. Power’s 2026 U.S. Retail Banking Satisfaction Study found that 20% of retail bank customers had moved money away from their primary bank during the preceding three months, versus 17% in the previous study. Yet overall satisfaction increased two points to 657 on a 1,000-point scale. The study covered 107,059 customers, with fieldwork from January 2025 through January 2026, before October’s supervisory reporting.5
That combination should make CMOs suspicious of reassurance measured only through brand sentiment. A customer can report a satisfactory experience while moving balances elsewhere. Equally, moving money does not necessarily mean abandoning the bank. Retention analysis needs to distinguish relationship closure, reduced share of wallet and ordinary balance movement.
The budget question is which automation improves relationship economics after all costs are counted. A proposed management test is:
Incremental contribution = incremental retained and acquired relationship contribution + genuine servicing savings − technology, oversight, escalation and remediation costs.
This is a decision framework, not an industry benchmark. Use Finance-approved contribution values, avoid double-counting savings and do not treat retained deposit balances as revenue. Model-access fees are not the whole investment.
The tradeoffs matter. A personalized fee-avoidance alert could reduce fee income while improving retention. A chatbot could lower cost per contact while generating more repeat contacts. Track cost per resolved customer need, complaint incidence and incremental relationship contribution alongside conversion—not instead of them.
The architectural implication is specific: separate an assistant’s permission to explain an offer from its authority to execute an action. Marketing should define permitted propositions, claims and customer permissions. Product and technology teams should enforce the boundaries; operations should own staffed escalation; risk and compliance should validate the controls and obligations.
Marketing automation also needs a verified way to recognize affected customers during a service incident, using only the necessary status data. Otherwise the bank can have a technically functioning campaign engine delivering commercially damaging messages. The CMO need not certify the infrastructure, but should withhold launch support when the service owner cannot demonstrate the customer promise. Ironically, all of this can be done with AI.
Frontier take
Reputational exposure is plausible. A fear of an AI-driven customer exodus is not established. The reviewed evidence does not measure whether AI is CMOs’ leading reputational concern or whether marketing teams are unprepared. Nor does it establish a flight from bank deposits into commodities. Pricing, convenience and service remain competing explanations that customer research should test before marketing funds a fear-led retention campaign.
The suggestion that regulators consider operations while ignoring customer experience also fails scrutiny. The FCA explicitly addresses customer understanding and support. Separately, Citizens Advice’s July 6, 2026 submission to the Mills Review reported clients acting on poor AI-generated advice and advisers struggling when clients trusted AI answers over regulated advice. These are meaningful frontline observations, but they do not establish prevalence across banking or show that bank-deployed agents caused those cases.46
Hyperpersonalization is therefore a candidate intervention, not the proven cure. There is evidence that customers distinguish useful assistance from automated selling. J.D. Power research published September 5, 2024, based on 2,001 financial-services customers surveyed in April 2024, found that 62% of bank customers were willing to try AI-driven alerts to avoid fees, compared with 42% willing to accept personalized product recommendations from an AI agent. These percentages concern bank customers within the wider sample. They measure stated willingness, not observed retention, and are older than the current supervisory developments.7
The useful distinction is not personalized versus impersonal. It is helpful personalization versus sales personalization. A timely explanation, permission-based alert or faster resolution may earn more trust than an offer assembled from increasingly intimate data. That proposition needs testing, not another adjective in the campaign brief.
The credible counterargument is that excessive caution preserves expensive, frustrating legacy service. An AI service could be faster, more consistent and easier to access than the existing alternative. Requiring a person in every interaction would confuse accountability with manual processing.
The answer is to make automation compete on completed customer outcomes. The recovery-first thesis would weaken if controlled deployments showed broader autonomous personalization delivering superior cost-adjusted retention without worsening errors, complaints, exclusion or privacy concerns. And if customer research finds negligible AI anxiety while rates or ordinary service explain lost business, an AI-trust campaign would be solving the wrong problem.
Three moves for CMOs
-
Make a recoverable customer journey a launch condition. Require an approved explanation of what customer-facing AI can do, an appropriately governed record of material interactions and a tested path to someone empowered to resolve problems. Obtain named commitments from product, operations, technology and compliance. Decision boundary: withhold campaign support for autonomous changes to money, product terms or material customer commitments unless explicit authorization, escalation and recovery controls are demonstrated. Why now: supervisors are examining agent boundaries and recovery. For affected ECB-supervised institutions, the October 31 action-plan deadline is an immediate coordination point—not a new CMO-owned regulatory obligation.12
-
Make personalization compete for its budget. Reserve part of proposed AI-marketing spending for controlled comparisons of personalized alerts, straightforward AI guard-railed and rules-based messages as well as human-assisted resolution. Agree observation periods and Finance-approved measures of incremental relationship contribution, resolution cost, repeat contacts and complaints before starting. Decision trigger: scale only when benefits survive full-cost accounting and pre-agreed customer-harm limits; pause immediately for unauthorized financial and Cx actions. Why now: the retail-banking evidence shows money moving despite slightly higher aggregate satisfaction, but establishes neither AI as the cause nor personalization as the remedy. Conversion alone is an inadequate investment case.5
-
Rehearse the customer response before buying reassurance. Run a joint exercise covering incorrect AI advice, disrupted account access and a compromised service provider. Prepare verified status messages, accessible alternatives, urgent-needs routing and complaint handling. Make incident-based promotional suppression part of the exercise. Decision trigger: suspend sales automation for affected customers when material service accuracy or access becomes uncertain; resume when the accountable service owner confirms it is appropriate. Create a dedicated human-in-the-loop response team to elevate any customer experience degradation. Communicate confirmed facts without speculative recovery promises. Why now: the Bank of England’s assessment supports contingency preparation, even though catastrophe is not established.3 The strongest trust message is a recovery experience the bank can actually deliver.
[^boe-september30][^fca-october2][^jdpower-retail2026]